Ask a roomful of Indian savers where the safest money in the country sits, and one answer comes back almost every time: the Public Provident Fund. Ask the same room where long-term wealth gets built, and the usual answer is mutual funds — an equity SIP, held for years.
Both answers are popular, and both are incomplete. PPF and mutual funds are not two versions of the same thing. They are different tools, built for different jobs, with different rules about risk, tax and access to your money. Put ₹1.5 lakh a year into each for 15 years and the outcomes look very different — and the reasons behind the gap matter more than the final numbers.
This article compares the two side by side: how PPF works, what 15 years of PPF actually builds at today's rates, what the same money in an equity SIP could build at different assumed returns, and which kind of goal each one suits.
How PPF actually works
The Public Provident Fund is a government-backed small savings scheme, opened through banks and post offices. It has four features that explain its reputation.
A government-set interest rate. PPF currently earns 7.1% per annum — the rate fixed by the Finance Ministry for the October–December 2026 quarter (notification of 30 September 2026). The rate has now stood at 7.1% since April 2020, but it is reviewed every quarter, so today's rate is not a 15-year promise. A future quarterly review can raise it or lower it.
A long, fixed term. A PPF account runs for 15 financial years. After maturity, the account can be extended in blocks of five years, with or without fresh deposits. Partial withdrawals are allowed from the seventh financial year — one withdrawal per financial year, subject to a cap linked to earlier balances — and a loan facility exists between the third and sixth financial years. PPF money is not meant to be touched early, but it is not entirely locked away either.
Strict deposit limits. An individual can deposit between ₹500 and ₹1.5 lakh in a financial year, and can hold only one PPF account in their own name. A parent can additionally open an account for a minor child.
Triple tax exemption — the EEE status. Deposits qualify for a deduction under Section 80C (within the overall ₹1.5 lakh Section 80C limit), the interest earned is tax-free, and the maturity amount is tax-free. That EEE treatment is the reason PPF often wins tax comparisons — though the tax rules described here are those in force on the date of this article, and tax rules can change.
One more PPF detail matters for the arithmetic below: interest is calculated on the lowest balance in the account between the 5th and the last day of each month. A deposit made by 5 April therefore earns interest for the full financial year, while a deposit made late in the month earns interest only from the following month. Timing, for once, is free money.
What 15 years of PPF actually builds
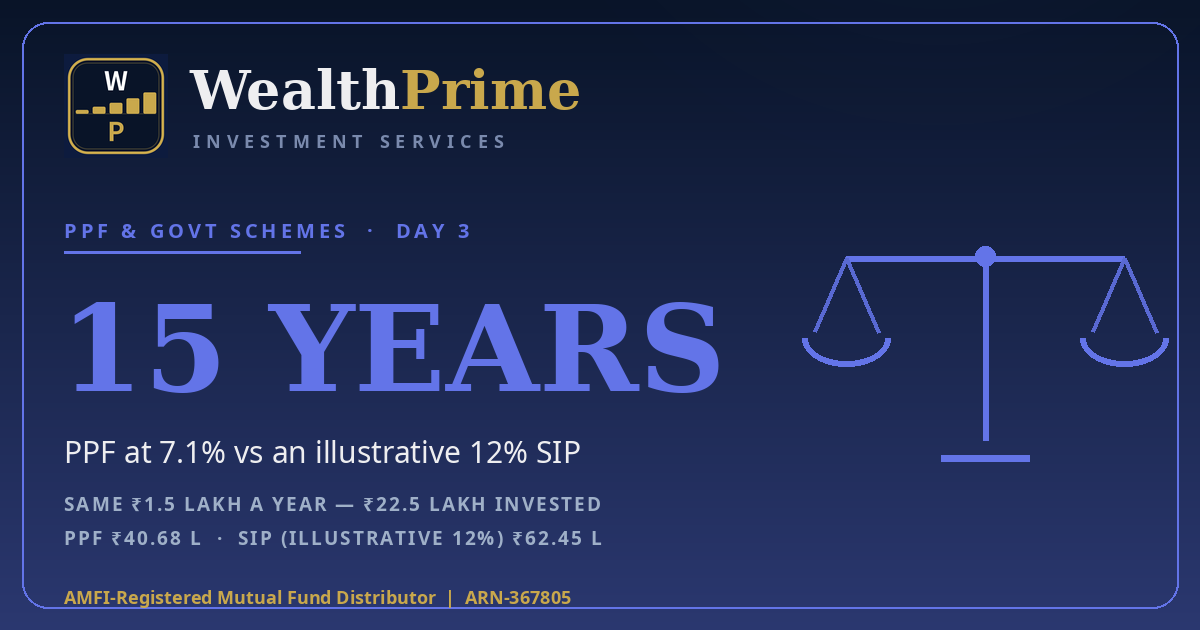
Take an investor who deposits the maximum — ₹1.5 lakh — at the start of each financial year, by 5 April, for 15 years. The total invested is ₹22.5 lakh.
At 7.1% per annum compounded annually, and assuming the rate stays at 7.1% for the full 15 years, that account matures at approximately ₹40.68 lakh. The interest earned is about ₹18.18 lakh on top of the ₹22.5 lakh deposited.
Two honest caveats belong next to that figure. First, the rate assumption: 7.1% has held for over six years, but it is reset every quarter, so the actual maturity amount will move with future reviews. Second, inflation: a fixed-rate return is worth less in real terms if prices rise. If inflation averages 5% a year, a 7.1% nominal return is roughly a 2% real return — the money grows, but its purchasing power grows slowly. PPF protects the nominal value of the money completely; it does not protect its purchasing power completely.
Readers who want to test their own deposit pattern can run the numbers on our PPF calculator, which models deposits, interest and maturity year by year.
The mutual fund side of the same ₹1.5 lakh
Now invest the same ₹1.5 lakh a year differently: ₹12,500 a month through an equity mutual fund SIP, for the same 15 years. The total invested is identical — ₹22.5 lakh, in 180 monthly instalments.
At an assumed 12% per annum compounded monthly — an illustration, not a forecast or a promise — the SIP grows to approximately ₹62.45 lakh. That is about ₹21.77 lakh more than the PPF figure above, from the same total investment.
But the assumed rate does all the work here, so it deserves a sensitivity check:
- At an assumed 10% per annum, the same SIP builds approximately ₹51.81 lakh.
- At an assumed 8% per annum, it builds approximately ₹43.25 lakh — only about ₹2.57 lakh more than the PPF outcome.
That last line is the most important number in this article. The mutual fund advantage over PPF is not automatic. It depends entirely on the return actually earned over the period, and equity returns vary from year to year — including years when the value falls. Past performance is not indicative of future returns, and no equity return can be promised in advance.
Tax narrows the gap further. Equity mutual fund gains held for over a year are taxed as long-term capital gains at 12.5% on gains above ₹1.25 lakh in a financial year, while PPF maturity is entirely tax-free under current rules. The post-tax comparison is therefore closer than the headline figures suggest, and the exact tax outcome depends on the investor's other gains and the rules in force at withdrawal.
Readers comparing fund categories before starting a SIP can compare equity fund categories in the explorer, which lists categories side by side with expense ratios and fund details — facts, not recommendations. And the monthly maths for any SIP amount can be checked on our SIP calculator.
PPF vs mutual funds: the comparison
| Feature | PPF | Equity mutual fund (SIP) |
|---|---|---|
| Backed by | Government of India | Market-linked securities; no government backing |
| Return | 7.1% p.a. currently, reset every quarter | Varies with markets; not fixed or predictable |
| Term / lock-in | 15 years; extension in 5-year blocks | No lock-in (except ELSS, 3 years); redeemable any working day, though an exit load may apply |
| Access before maturity | Partial withdrawal from the 7th year; loan in years 3–6 | Redemption available, but the value depends on the market on that day |
| Tax on exit (current rules) | Fully tax-free (EEE) | LTCG 12.5% above ₹1.25 lakh a year; STCG 20% |
| Minimum | ₹500 per year | SIPs from ₹100–₹500 a month depending on the scheme |
| Risk | No market risk; only rate-reset risk | Market risk; value can fall |
| Typically used for | A safe, tax-free base; goals needing certainty | Long-term growth goals, 10 or more years away |
The 15-year truth: three differences that decide it
1. The kind of uncertainty is different. PPF's uncertainty is the quarterly rate review: the return is known for the current quarter and unknown beyond it. A mutual fund's uncertainty is the market: returns are unknown in every period, and can be negative. One uncertainty is small and slow-moving; the other is large and fast-moving. Investors who cannot sleep through a 20% portfolio fall are not being irrational — they are describing a real cost of the equity route.
2. Tax treatment changes the ranking. On pre-tax figures at an assumed 12%, the SIP leads by about ₹21.77 lakh. After equity capital gains tax, the lead shrinks. For investors with large gains, the post-tax gap is smaller still. Comparing pre-tax mutual fund figures with tax-free PPF figures flatters the mutual fund side — always compare post-tax where possible.
3. Behaviour decides more than arithmetic. PPF's lock-in enforces patience: the money stays put because leaving is difficult. A SIP's flexibility is a strength and a weakness — stopping during a market fall locks in the worst timing. The investors who actually earn the illustrative SIP figures are the ones who kept every instalment going, including instalments made while markets were falling. Our earlier comparison of SIP vs FD makes the same point from the other side: the product matters less than the habit of staying invested.
Which goal goes where — and why many investors use both
The practical answer is rarely "PPF or mutual funds" — it is "PPF for which goal, mutual funds for which goal".
Goals that need a known sum on a known date — a child's school fee instalment, the safe portion of a retirement plan, money that cannot afford a market fall — fit PPF's stability and tax-free maturity. Goals a decade or more away, where growth matters more than stability and where a fall can be waited out — retirement saving in one's 30s, a child's higher-education fund started early — are the goals for which equity SIPs are commonly used, with the market risk accepted consciously.
Many salaried investors therefore hold both: PPF as the safe, tax-free base, and a SIP as the growth engine. The split between them is a personal decision based on the goal, the time horizon and comfort with market ups and downs — there is no single split that suits everyone, and no article can set it for a reader it has never met.
One rule of thumb survives every comparison: money needed within the next year or two, and the emergency buffer, should be in neither of these two — the first because of lock-in, the second because of market risk. Keep that money in a liquid, instantly accessible place, and let PPF and SIPs handle the long term.
PPF protects money from markets; mutual funds expose it to markets in exchange for growth potential. On the same ₹1.5 lakh a year for 15 years, PPF at an unchanged 7.1% builds about ₹40.68 lakh, while an equity SIP at an illustrative 12% builds about ₹62.45 lakh — but only if that return is actually earned, and only for investors who stay invested through the falls in between.
Frequently asked questions
Is PPF better than mutual funds?
Neither is better in general — they do different jobs. PPF suits money that needs capital stability and a tax-free maturity, with a 15-year horizon and limited early access. Equity mutual funds suit long-term growth goals where the investor accepts market ups and downs in exchange for higher growth potential. Many investors hold both, for different goals.
Can I invest in both PPF and mutual funds?
Yes. There is no rule against holding both a PPF account and mutual fund investments. A common approach is to use PPF as the safe, tax-free base and a SIP as the growth engine, with the split decided by each goal's time horizon and the investor's comfort with market risk. Emergency money should be kept separately, in a liquid and instantly accessible place.
Is PPF interest really tax-free?
Yes, under the rules in force on the date of this article. PPF has EEE tax status: deposits qualify for a deduction under Section 80C (within the overall ₹1.5 lakh limit), the interest earned is tax-free, and the maturity amount is tax-free. Tax rules can change, so the position should be re-checked in the year of withdrawal.
What happens to my PPF account after 15 years?
At maturity, the investor can withdraw the full balance, or extend the account in blocks of five years — with fresh deposits, or without them, letting the existing balance keep earning interest. Partial withdrawals are available from the seventh financial year, one per financial year, subject to a cap linked to earlier balances.
The bottom line
PPF and mutual funds are not rivals; they are different instruments. PPF offers government-backed stability, a quarterly-reset rate of 7.1% at present, and a fully tax-free maturity after 15 years. An equity SIP offers growth potential that depends entirely on market returns actually earned, taxed on exit, with no certainty attached. On the same ₹1.5 lakh a year, the 15-year illustration gives roughly ₹40.68 lakh from PPF against roughly ₹62.45 lakh from a SIP at an assumed 12% — and roughly ₹43.25 lakh at an assumed 8%, which shows how much the answer depends on the assumption. Match each goal to the tool whose risk, tax and lock-in fit it, and use both where two different goals are involved.
Sources: PPF rate and small-savings notification — Finance Ministry, Department of Economic Affairs, 30 September 2026 (7.1% for October–December 2026); PPF scheme rules on deposits, withdrawals, loans and extensions; mutual fund figures are the author's own illustrative calculations at assumed rates, stated in the article, and are not scheme data or forecasts. Tax rates are those in force on 2 November 2026 and can change.
Not Sure Which Fits Your Goal?
PPF and SIPs do different jobs. Talk to us on a free, no-pressure call about matching each goal to the right tool — no fund picks, no pressure.
Prefer chat? WhatsApp us